Huntington Mobile Banking

Screenshots
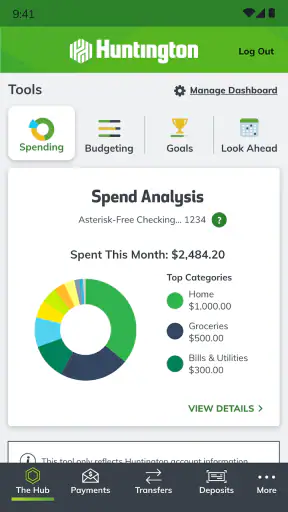
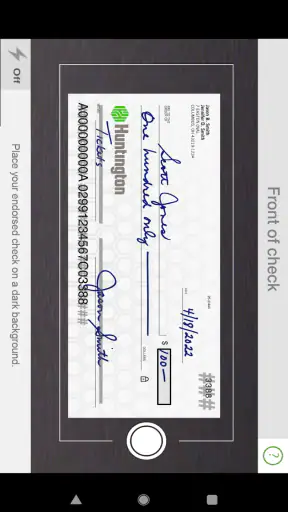
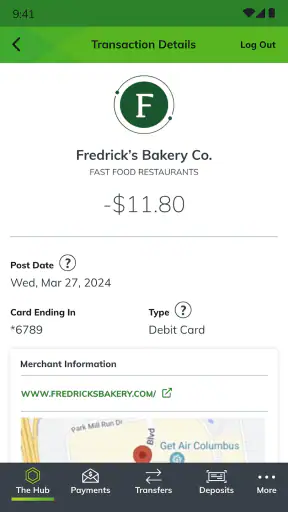
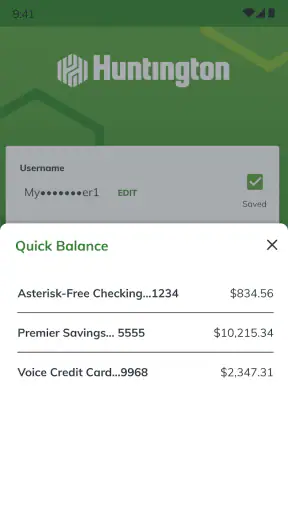
Details
- Rating
- 18.12K reviews
- Version
- 6.78.204
- Developer
- Huntington National Bank
Analysis by Norviv
I look at a banking app differently from a social or shopping app. It has to make routine money tasks feel clear, but it also has to earn trust every time I open it. Huntington Mobile Banking is the finance app from Huntington National Bank, and after using it as a day-to-day banking companion, I found its main appeal quite straightforward: it brings the bank account relationship onto a phone without trying to become a general-purpose financial dashboard.
That focus matters. If you already bank with Huntington, the app is designed to be the practical place for checking balances, reviewing activity, and handling ordinary account tasks while away from a computer. If you are comparing banks rather than simply choosing a mobile tool, the decision is broader. The app can make Huntington more convenient for existing customers, but a polished mobile experience alone is not a reason to move your entire financial life.
What I considered before recommending it
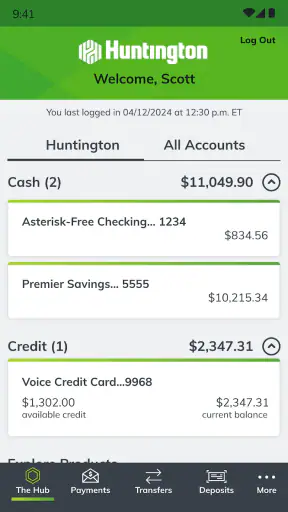
My first test for a banking app is not how many buttons it has. I want to know whether I can answer three questions quickly: how much money is available, what recently changed, and what action I can safely take next. Huntington Mobile Banking performs best when used for that kind of short, purposeful visit. Its store summary presents it as a way to manage bank accounts securely from a mobile device, and that is also how I experienced its role.
The app is free, carries an Everyone age rating, and comes from Huntington National Bank. It has been available since June 6, 2011, which gives it a long history as a mobile banking product rather than the feel of a newly assembled companion app. Its current version is 6.78.204 and it requires iOS or Android version 10 or later. Those details are worth checking before installation, especially if you keep an older phone for banking or use a device that no longer receives operating-system updates.
Trust is also part of the practical decision. Huntington Mobile Banking has an average rating of 4.8 from around 78,000 ratings, with roughly 18,000 written reviews, and it has passed one million installs. Those figures suggest that the app has a substantial user base and that many customers find it dependable. I would still treat ratings as context rather than proof: a banking app can be well reviewed overall and still have a workflow that does not suit the way you manage money.
I also judge whether an app helps me avoid mistakes. A useful banking screen should make it easier to distinguish current activity from older transactions, recognize an unfamiliar charge, and pause before confirming a sensitive action. With Huntington, I prefer using it when I already know what I want to do. That mindset reduces the temptation to explore randomly inside a financial account, and it makes the app feel more controlled.
The everyday scenario where it makes sense
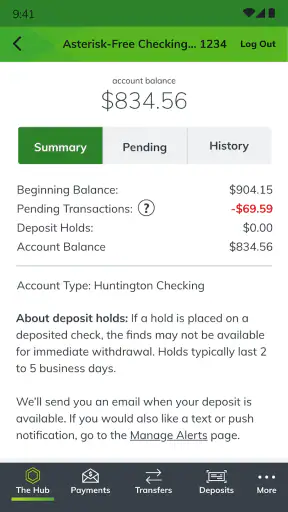
Imagine I am leaving a grocery store and want to check whether a recent payment has affected my available balance before I make another purchase. I open the app, review the account activity, and close it once I have the information I need. Later, I might return to confirm that a deposit or scheduled payment appears as expected. This is not a dramatic use case, but it is exactly where a mobile banking app earns its place: small checks that would otherwise require a browser, a phone call, or delayed attention.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
Another useful habit is reviewing transactions at a fixed time rather than opening the app repeatedly throughout the day. I can use the mobile view as a quick checkpoint, then reserve more involved budgeting decisions for a larger screen or a dedicated financial tool. That separation is important because a bank app is usually strongest at account access, not at replacing every spreadsheet, envelope system, or budgeting service.
Where Huntington’s app wins
The strongest advantage is the connection between the app and Huntington’s own banking relationship. When the bank already holds my accounts, there is less friction between seeing an account and acting on it. I do not need to assemble information from several institutions just to understand what is happening inside Huntington. For a customer who wants a direct mobile doorway to that bank, this is more useful than a broad finance app that mainly gathers information.
I also like the narrower purpose. A general money-management app may show spending across banks, cards, loans, and investments, but that wider view can introduce another layer between me and the institution handling a transaction. Huntington Mobile Banking is better suited to the person who wants to deal directly with Huntington rather than build a complete financial picture in one interface.
Its long availability is another quiet strength. A banking app that has existed for many years has had time to become part of a bank’s normal customer experience. That does not guarantee that every screen will be perfect, but it makes the app feel like an established channel rather than an experiment. The high average rating and large install base reinforce that impression without removing the need for personal testing.
For quick account awareness, the phone format is especially convenient. I can check activity while travelling, preparing a payment, or deciding whether to move money between planned expenses. The value is not that the app makes financial decisions for me. The value is that it shortens the distance between a question and the account information needed to answer it.
Three habits that make the app more useful
First, I recommend using transaction review as a reconciliation routine rather than waiting until a statement becomes a problem. A short review after regular spending helps me notice duplicate-looking entries, unfamiliar merchants, or timing differences while the purchase is still easy to remember. That is a more useful role for the app than simply checking the balance and moving on.
Second, I separate “available now” thinking from “safe to spend” thinking. A mobile balance can tell me what is visible in the account, but my own upcoming obligations may not be reflected in the way I mentally budget. I use Huntington’s account view as a source of current information, then compare it with bills, transfers, and commitments I already know about. This prevents a convenient balance check from becoming an accidental spending plan.
Third, I use the app as a confirmation point after important account activity. If I have arranged a payment or expect money to arrive, checking later can help me verify that the account reflects the change I anticipated. The key is to confirm the result rather than repeatedly guessing whether something has happened. That small distinction makes mobile banking calmer and less error-prone.
Where another category may fit better
Huntington Mobile Banking is not the obvious choice for someone who wants a complete view of several unrelated banks in one place. A dedicated budgeting or account-aggregation service may be better for that job because its primary purpose is comparison across institutions. I would choose that category when spending analysis, household budgeting, or a combined financial snapshot matters more than direct access to one bank.
It may also be the wrong starting point for someone who does not bank with Huntington. Installing a bank-specific app before deciding whether Huntington’s accounts, service model, and broader banking offering suit you puts the cart before the horse. The app improves access to an existing relationship; it does not, by itself, create a reason to open one.
People who prefer handling complex financial planning on a desktop may also find a phone limiting. A mobile screen is excellent for checking and confirming, but less comfortable for comparing many categories, studying long transaction histories, or building a detailed household plan. In that situation, I would use the app for timely account awareness and a larger interface for analysis.
There is a trade-off between simplicity and breadth here. A focused bank app can feel less cluttered than a financial super-app, but it will not necessarily replace tools designed for investments, taxes, credit monitoring, or multi-bank planning. I would not judge that as a flaw unless I expected Huntington’s app to cover those separate jobs.
The friction I would plan around
The first limitation is dependence on the Huntington relationship. The app’s usefulness is closely tied to whether Huntington is the institution I actually need to manage. Someone with accounts spread across several banks may still need other apps, a browser, or a separate financial organizer. The convenience is real, but it is concentrated rather than universal.
The second is the risk of mistaking access for guidance. Seeing account activity on a phone does not automatically explain why a balance changed, whether a future obligation is covered, or whether a purchase fits a longer-term plan. I appreciate the app more when I treat it as an accurate place to inspect my banking relationship, not as a personal financial adviser.
There is also the ordinary friction of using a financial app on a phone. A small display can make detailed review slower, and a user who changes devices or delays operating-system updates may need to think about compatibility. Because the minimum operating system is version 10, I would check the device before planning to make it my primary banking channel.
Finally, convenience can encourage overchecking. I do not think opening a banking app constantly improves financial control. A deliberate routine—checking after known activity and reviewing transactions regularly—is more useful than turning every notification or balance change into a reason to worry. The app supports that routine, but the discipline still comes from the user.
The real cost of switching
There is no purchase price for the app, so the financial barrier to downloading it is low. The larger cost appears when the decision is really about changing banks. Moving recurring payments, deposits, saved payment details, and personal routines takes more effort than installing a free application. I would not switch institutions solely because the mobile experience looks convenient.
If I already use Huntington, the switching cost is much smaller. I can evaluate the app as an additional access point rather than rebuilding my finances. My approach would be to install it, complete a few low-risk tasks, and see whether the account view and transaction review fit my habits before depending on it for time-sensitive activity.
For a prospective Huntington customer, I would compare the complete banking relationship separately from the app. Consider whether the bank meets your needs, then treat the mobile experience as an important convenience layer. This avoids a common mistake: choosing a financial institution based on a single screen while ignoring the work involved in moving established accounts.
Who should use it and who should skip it
I would recommend Huntington Mobile Banking to an existing Huntington customer who wants straightforward account access from a phone, checks transactions regularly, and values a direct connection to the bank. It is also a sensible fit for someone whose financial life is centered mainly on Huntington rather than scattered across many institutions.
I would be more cautious if your priority is a unified household dashboard, deep spending categorization, or detailed planning across multiple providers. In that case, a dedicated budgeting product may be a better primary tool, with the Huntington app retained for direct account confirmation. If you do not have a Huntington account and are only looking for a finance app, this is probably not the right category to start with.
Parents and families should also think about access habits before handing over a phone-based banking routine. The Everyone rating describes the app’s content classification, not a recommendation to give every family member unrestricted financial access. I would keep account credentials private and decide carefully who needs to view or manage banking information.
My final recommendation
Huntington Mobile Banking is a strong choice when your goal is direct, everyday control of Huntington accounts rather than all-in-one financial planning. I value it for quick balance awareness, transaction review, and the convenience of handling banking questions without opening a desktop browser. Its established history, free availability, broad adoption, and high average rating make it easy to take seriously.
My recommendation is conditional but clear: if you already bank with Huntington, install it and make it part of a measured account-review routine. Use it to confirm what is happening, not to replace your budget or make rushed decisions. If you are comparing banks, evaluate Huntington as a complete institution first and the app second. And if your main need is a cross-bank financial command center, choose a tool built for that category instead.
After weighing those differences, I see Huntington Mobile Banking as a practical companion rather than a universal money solution. That is not a weakness. For the right customer, a focused app that makes ordinary banking easier is exactly what should be installed on a phone.
My verdict: recommended for Huntington customers who want convenient mobile account management; less suitable as a standalone finance app for people seeking multi-bank budgeting or broader financial planning.
Frequently Asked Questions
01What is Huntington Mobile Banking, and what can I do with it?
Huntington Mobile Banking is the official mobile app for Huntington customers who want to manage their accounts from an Android or iOS device. After signing in, you can check balances, review transactions, transfer money between eligible accounts, deposit checks, pay bills, locate branches and ATMs, and receive account alerts. Available features may depend on your account type, device, and enrollment status.
02Is Huntington Mobile Banking safe to use on my phone?
The app includes security features designed to protect your banking information, such as secure sign-in, encryption, device authentication, and alerts for account activity. You should still use the latest app version, keep your phone’s operating system updated, avoid public Wi-Fi when possible, and never share your password or verification codes. Huntington may also require additional identity verification for certain actions.
03Can I deposit checks through the Huntington Mobile Banking app?
Eligible customers can generally use the app’s mobile check deposit feature by photographing the front and endorsed back of a check. The images must be clear, and the check should meet Huntington’s deposit requirements. After submission, keep the original check until the deposit is fully processed. Deposit limits, availability times, holds, and eligibility can vary, so review the app’s instructions before relying on the funds.
04Does Huntington Mobile Banking support bill payments and money transfers?
The app allows eligible users to handle common payment and transfer tasks, including paying enrolled bills, moving money between Huntington accounts, and, where available, transferring funds to external accounts or sending money through supported services. Processing times, transfer limits, fees, and recipient eligibility may differ. Always confirm the destination, amount, and scheduled date before submitting a transaction.
05What should I do if I cannot log in or the app is not working properly?
If Huntington Mobile Banking will not open or you cannot sign in, first check your internet connection and confirm that the app and your phone software are updated. Restarting the device can also help. Use the official password or username recovery options rather than repeatedly guessing credentials. If the issue continues, contact Huntington through its verified support channels and avoid downloading unofficial versions of the app.


